CAPITAL SOLUTIONS · GOLD FINANCE

Unlock Your Gold's Value.
Instant, Secure Financial Support.

Need immediate liquidity for personal milestones, urgent medical needs, agricultural expenses, or business working capital in Kerala? Capital Solutions helps you evaluate trusted gold loan options, understand per-gram valuation and RBI LTV limits, compare flexible repayment schemes, and choose regulated banking or NBFC partners.
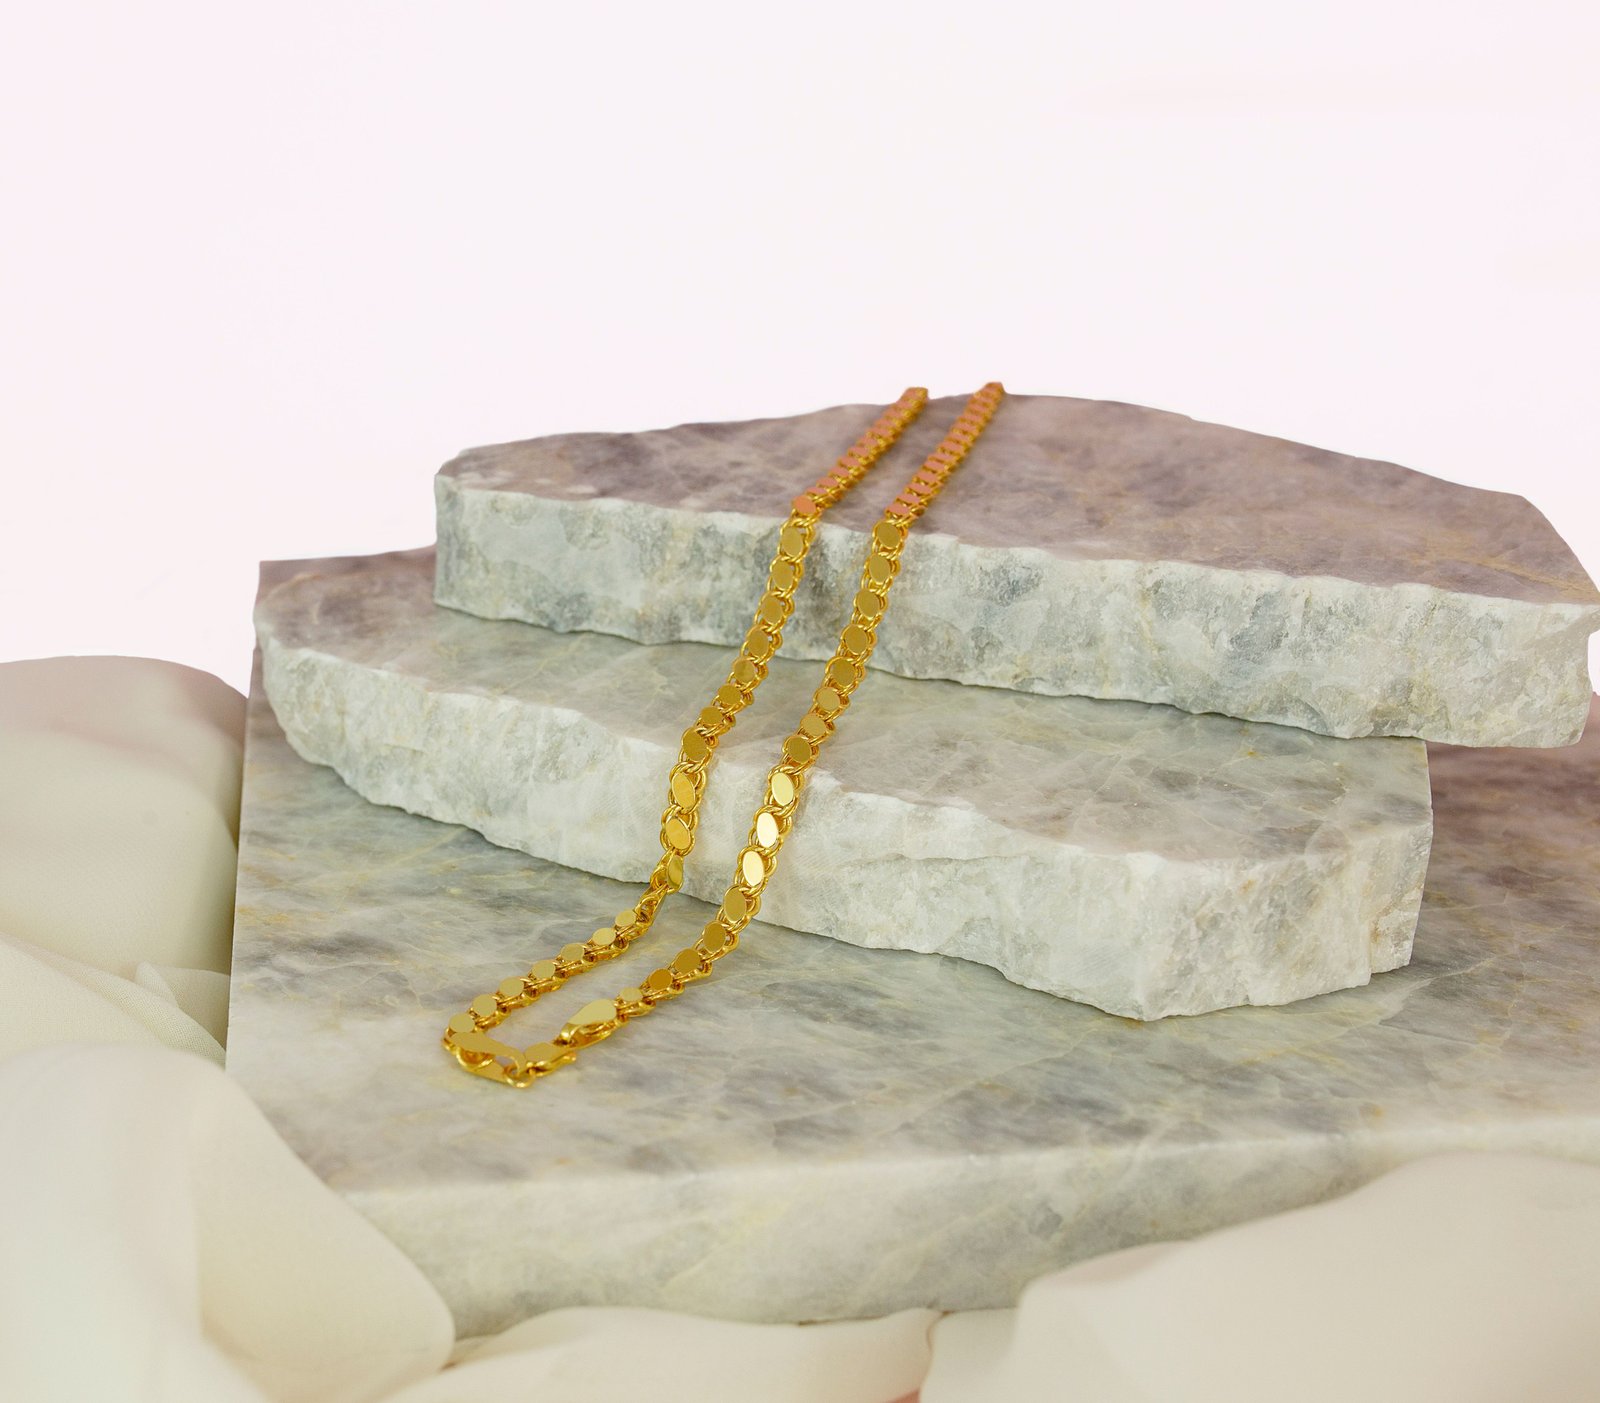
Gold loan assistance and jewellery valuation in Kerala by Capital Solutions
01. Instant Liquidity
Quick disbursement against 18k to 22k gold jewellery with minimal formalities.
02. Flexible Repayment
Choose regular EMI, bullet repayment, or interest-only payment structures.
03. Certified Vault Security
Secure storage in bank-grade, insured safe vaults until complete redemption.
04. Loan Takeover / Transfer
Switch high-interest gold pledges to banks offering lower interest rates.
SMART ASSET LEVERAGE

Turn Your Idle Gold into Working Capital with Complete Safety

Gold jewellery is one of Kerala's most trusted household assets. Instead of selling family heirlooms during unexpected cash crunches, a gold loan allows you to raise short-term capital quickly at competitive rates, while keeping ownership securely intact in institutional bank lockers.

Whether you are an entrepreneur in Thrissur managing business payroll, a trader in Kochi bridging inventory cycles, an agriculturist, or a salaried individual handling emergency expenses, compare Loan-to-Value (LTV) limits, purity valuation norms, and interest schemes before pledging.

Discuss Your Gold Loan →
01

Rapid Disbursement

On-the-spot karat testing, appraising net gold weight, and direct cash or instant bank transfers within minutes.

02

Minimal Paperwork

No complex income certificates, salary slips, or business ITRs required; simple KYC proofs and gold purity suffice.

03

Tailored Repayment Plans

Select flexible interest servicing options, monthly instalment plans, or bullet settlements upon loan maturity.

04

Bank Locker Storage

Pledged ornaments are sealed, weighed, fully insured, and stored in high-security bank vaults until redemption.

Important: Per-gram loan values, maximum LTV caps, interest slabs, and locker custody charges are regulated under RBI directions and institutional lender policies.
KNOW BEFORE YOU PLEDGE

Gold Loan Eligibility Criteria

Gold loans are asset-backed facilities, meaning traditional credit barriers like high CIBIL score thresholds or lengthy income histories are rarely strict constraints. Eligibility primarily centres around the purity, net weight, and ownership of your gold ornaments.

The sanctioned amount is determined strictly according to the statutory Loan-to-Value (LTV) cap (mandated up to 75% of the prevailing 30-day average gold price by the RBI) after deducting stone weights and impurities.

Check Your Eligibility →
01

Age & Resident Status

Any Indian resident aged 18 years and above owning genuine gold ornaments or certified gold coins can apply.

02

Gold Purity Range

Accepted jewellery must have a purity ranging from 18 to 22 karats. 24 karat bullion bars/coins are generally subject to specific bank limits (e.g., 50g per customer).

03

Net Weight Assessment

Certified appraisers deduct stones, gems, beads, and wax weight to calculate the precise net weight of pure gold.

04

Ownership Declaration

The applicant must be the lawful owner of the jewellery and sign a self-declaration of ownership during pledge creation.

Important: Lenders cannot accept gold bullion bars, spurious ornaments, or gold belonging to minors. Valid KYC verification is mandatory for every borrower.
PREPARE YOUR APPLICATION

Documents Required for Gold Loans in Kerala

Gold loans require minimal paperwork. Having standard identity and residence verifications ensures your loan can be disbursed in a single branch visit.

A

Identity & KYC Proof

Essential official documents needed to establish KYC compliance with the bank or lending NBFC.

  • Permanent Account Number (PAN) Card or Form 60.
  • Passport, Voter ID, or Driving License.
  • Permitted KYC verification method or national identity proof.
  • Recent passport-sized photographs of the borrower.
  • Signed borrower application form and pledge declaration.

Providing a PAN is mandatory for high-value gold loans exceeding statutory transaction limits.

B

Residential Address Proof

Documents validating the current and permanent residential address of the borrower.

  • Recent electricity bill, water bill, or landline statement.
  • Active registered rent/lease agreement (if living in rented premises).
  • Updated bank passbook or statement with address details.
  • Property tax receipt or Kerala municipal residential certificates.
  • Ration card or local self-government issued resident certificates.

Verification of local residence is essential for postal correspondence and auction notices in default cases.

C

Ornament Documentation & Appraisals

Verification records generated during the physical testing and pledge of ornaments.

  • Purchase invoices or original jeweller receipts (recommended for high quantities).
  • Certified appraisal voucher generated by the lender’s internal valuer.
  • Gross weight, stone weight, and calculated net gold weight certificate.
  • Photographic record of the pledged jewellery pieces for safe custody.
  • Signed counterfoil of the tamper-proof security pouch.

The borrower receives a counter-signed copy of the assay sheet documenting the exact items deposited.

D

Takeover / Balance Transfer Records

Documents needed when transferring a pledged gold packet from another financier or local pawnshop.

  • Original pledge card/token or pawn ticket from the current lender.
  • Updated statement of outstanding principal and accrued interest.
  • Provisional closure or release letter confirming total redemption balance.
  • Bank account statement for direct settlement or RTGS fund transfer.
  • Customer authorization letter allowing handover to the new financier.

Our advisors assist with direct cheque or online settlement to release and re-pledge jewellery smoothly.

TRANSPARENT GOLD PLEDGING

Gold Loan Interest Schemes, Fees & RBI Regulations

Compare per-gram valuations, interest compounding frequency, appraisal charges, and regulatory borrower safeguards before pledging your gold.

₹

Interest Rate & Schemes

Schemes range from low-interest monthly servicing models to bullet repayment plans. Carefully review the Annual Percentage Rate (APR) to evaluate the true annual cost of credit.

02

Appraisal & Vault Charges

Check nominal one-time assaying/appraiser fees, processing charges, and insurance or locker custody fees levied by the lending institution during pledge creation.

03

Foreclosure & Auctions

Understand notice periods, auction triggers on overdue accounts, grace periods, and any zero-prepayment penalty privileges for premature closure.

Critical borrower protections & regulatory safeguards

  • RBI Loan-to-Value (LTV) Cap: Under Reserve Bank of India directions, lenders must calculate gold value on a 30-day moving average of 22k gold and cannot exceed a statutory 75% LTV cap, safeguarding borrowers against market volatility.
  • Standard Key Facts Statement (KFS): Borrowers must be provided with a KFS detailing the sanctioned amount, net weight, interest calculation method, APR, tenure, and all incidental costs before signing the contract.
  • Mandatory Safe Custody & Insurance: Lenders are legally obligated to insure all pledged ornaments against burglary, theft, or fire and keep them locked inside dual-custody strongrooms.
  • Fair Auction Procedures: In case of prolonged default, lenders cannot arbitrarily seize ornaments. They must issue statutory notices, conduct public auctions through registered auctioneers, and refund any surplus proceeds to the borrower.
  • No Hidden Prepayment Penalties: Most regulated banks and leading NBFCs permit borrowers to repay principal or close gold loans before maturity without unfair prepayment or foreclosure penalties.
  • Transparent Weight Records: Every borrower receives an official duplicate pledge ticket recording gross weight, stone weight, net weight, and detailed descriptions of ornaments pledged.
READ BEFORE PLEDGING

Gold Loan Terms & Conditions

Understand the essential contractual stipulations, custody obligations, and redemption guidelines before pledging ornaments.

1. True Ownership of Ornaments

The borrower certifies full legal title to the jewellery. Pledging spurious, stolen, or third-party gold without proper legal authorization attracts severe penal consequences.

2. Karat & Weight Deductions

The lending bank's certified appraiser makes final deductions for non-gold components including solder, stones, threads, and internal wax cores to establish true net gold weight.

3. LTV Adjustments & Margin Calls

If market gold prices drop sharply during the loan tenure, lenders may ask the borrower to deposit additional margin or make partial payments to maintain regulatory LTV limits.

4. Servicing & Default Interest

Interest must be cleared as per the agreed scheme schedule. Delay beyond grace periods will attract penal charges as permitted under RBI regulations.

5. Vault Custody & Inspection

Pledged articles are held under dual-custodial bank lockers. The borrower receives an acknowledgement of packet numbers and seal impressions for safe retrieval.

6. Redemption & Handover

Ornaments are returned directly to the applicant upon full settlement of principal, interest, and any incidental charges, after verifying the original pledge card and ID.

7. Auction on Non-Redemption

In cases of persistent non-payment, the lender has the legal right to auction the pledged ornaments after serving mandatory written notices, returning any surplus balance.

8. Data Privacy & Regulatory Norms

Borrower identity records and transactions are reported to credit bureaus and maintained confidentially according to statutory digital data guidelines.

Capital Solutions service disclaimer

This platform provides informational guidance, gold valuation assistance, comparison, and document coordination. Capital Solutions is not an RBI-regulated bank or NBFC, and does not directly store gold or make credit decisions. Final valuation, purity confirmation, per-gram loan offers, and disbursement are executed exclusively by regulated banking and NBFC partners under RBI frameworks.

Explore Gold Loan Options Across Kerala

Kerala maintains one of the highest per-capita gold ownership rates in the country, making gold loans the preferred option for fast, hassle-free credit. A transparent gold pledge eliminates extensive paperwork, lengthy underwriting queues, and harsh credit score hurdles.

Capital Solutions helps families, small business owners, and farmers across Kerala navigate institutional gold finance. Compare leading nationalised banks, private banks, and NBFCs to lock in the highest per-gram valuation and the lowest interest rates.

All you need is basic KYC documentation: a government-issued photo ID (PAN card, Passport, Voter ID, or national ID proof), a recent residence address proof, passport photographs, and the gold jewellery for on-site purity testing.
The per-gram rate is determined by the 30-day average market price of 22k gold published by commodity associations, subject to the RBI's mandated maximum Loan-to-Value (LTV) ceiling (usually up to 75%).
Yes. Institutional lenders store pledged jewellery in tamper-proof, sealed packets placed in reinforced, dual-custodial bank lockers protected by CCTV surveillance, armed security, and full insurance coverage.
QUICK CHECKLIST

Before You Pledge

  • Check your gold's hallmark and karat purity (18k to 22k).
  • Account for stone and enamel weight deductions.
  • Verify today's per-gram loan rate across banks vs NBFCs.
  • Choose your preferred repayment scheme (monthly EMI vs bullet).
  • Carry valid PAN card and original address proof.
  • Inspect the seal and packet numbers on your pledge voucher.
  • Review processing charges, valuation fees, and late penal rules.
  • Read through the standardized Key Facts Statement (KFS).
Request Valuation Guidance →

Final loan approval, valuation criteria, and per-gram disbursals are executed by partner financial institutions.

YOUR QUESTIONS ANSWERED

Gold Loan FAQs

Answers to common questions regarding gold loan eligibility, valuation methods, repayment schemes, and safety measures.

01 What is a gold loan?
A gold loan is a secured loan where a borrower pledges gold ornaments or coins as collateral with an institutional lender in exchange for immediate liquid funds, redeeming the gold upon full repayment.
02 Who can apply for a gold loan in Kerala?
Any Indian citizen aged 18 and above who owns genuine gold ornaments (salaried, self-employed, homemakers, students, or farmers) can apply with standard KYC documents.
03 What purity of gold is acceptable?
Most lenders accept jewellery with purity between 18 Karat and 22 Karat. Gold coins sold by banks (up to 50 grams per borrower) are also accepted by select banks.
04 What is a bullet repayment scheme in gold loans?
Under a bullet repayment plan, you don't need to pay regular monthly EMIs; you pay the entire principal and accumulated interest as a single lump sum at the end of the loan tenure.
05 How does the lender determine the value of the gold?
Certified appraisers weigh the jewellery and test purity, excluding the weight of stones, gems, or wax. The net gold weight is then multiplied by the RBI-approved benchmark rate.
06 What is a Key Facts Statement (KFS)?
A KFS is an RBI-mandated document given to the borrower prior to sanction, clearly stating the exact loan amount, interest rate, APR, appraisal charges, and all applicable terms.
07 Are there prepayment charges on gold loans?
Most regulated banks and NBFCs charge zero prepayment penalties, allowing you to close your gold loan ahead of tenure and retrieve your ornaments whenever convenient.
08 Can I transfer my gold loan from another bank or financier?
Yes, a gold loan takeover/balance transfer allows you to switch your pledge to another lender offering lower interest rates or higher per-gram valuation.
09 What happens if I cannot repay on time?
Lenders offer grace periods and notice reminders. If default persists after statutory notices, the lender may auction the ornaments publicly, returning any excess proceeds to you.
10 Can someone else collect my gold ornaments upon redemption?
Generally, the original borrower must be physically present with identity verification. In exceptional circumstances, a formally authorized representative with a legal power of attorney can redeem it.
11 Does Capital Solutions guarantee gold loan disbursement?
No. Capital Solutions provides comparison, guidance, and document facilitation. Final assaying, credit approval, and disbursement are conducted solely by partner banks and NBFCs.
12 How do I enquire about a gold loan in Kerala?
Click the WhatsApp enquiry link to connect with our team. Share your estimated gold quantity. Never send sensitive financial PINs or passwords over chat.