CAPITAL SOLUTIONS · BESPOKE AUTO FINANCE

Exquisite Performance.
Luxury Car Finance.

Acquiring a marquee luxury marque in Kerala? Capital Solutions provides high-touch advisory for premium and exotic vehicle purchases. From high-ticket sanctions and structured balloon repayments to corporate tax structuring and discreet underwriting, we assist you in securing bespoke terms through premier private banks and specialty wealth lenders.

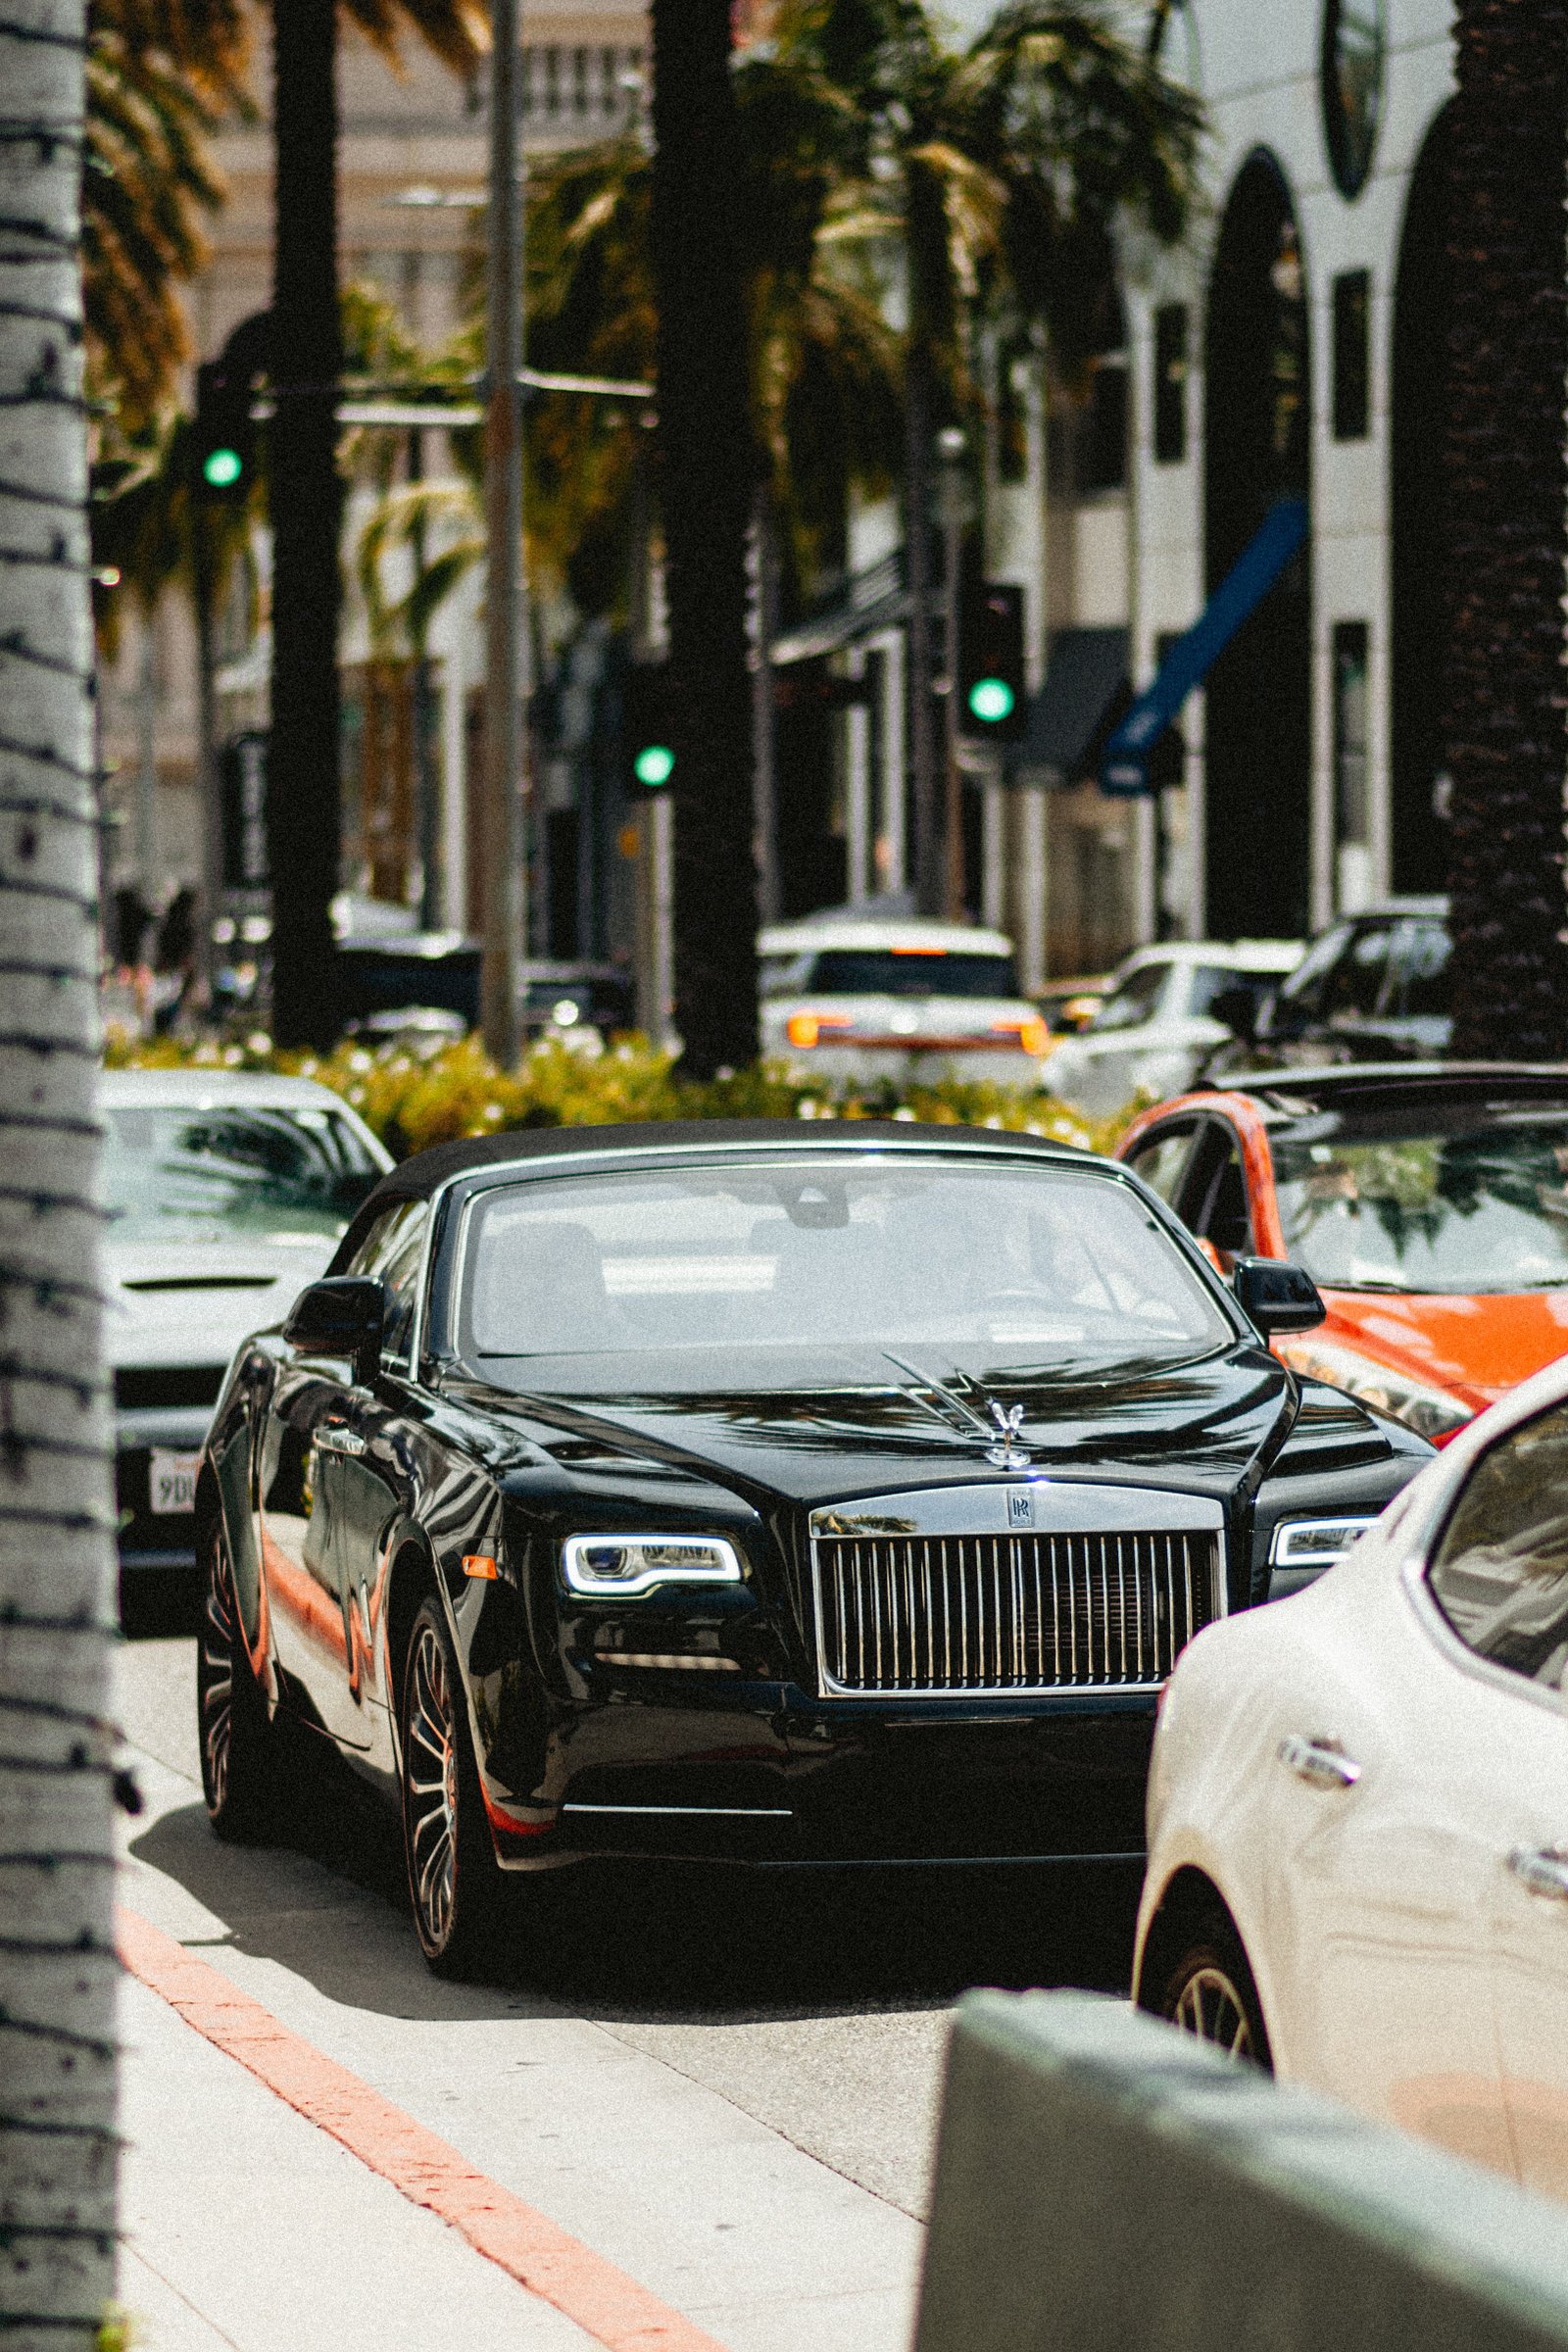
Luxury vehicle finance and premium car loan advisory by Capital Solutions in Kerala
01. New Luxury Cars
Financing for Mercedes-Benz, BMW, Audi, Porsche, Range Rover, and super-luxury marques.
02. Pre-Owned Exotics
Structured funding for verified pre-owned luxury and sports cars with clean pedigree.
03. Corporate & Lease Lines
Corporate borrower structures designed for tax-efficient depreciation and GST optimization.
04. Luxury Refinance
Equity release and high-value liquidity unlocks against unencumbered premium vehicles.
PREMIUM ASSESSMENT STANDARDS

Luxury Vehicle Loan Eligibility

Lending institutions evaluate luxury car applicants on holistic financial health. Beyond basic income checks, underwriting focuses on verified debt serviceability, audited business strength, investment portfolios, and credit discipline.

Consult on Eligibility →
01

Target Applicant Profile

Business promoters, corporate directors, partners, high-earning CXOs, doctors, NRIs, and established family enterprises with stable annual revenue streams.

02

Income & Profitability

Substantial minimum net annual income (typically ₹15L–₹25L+ for individuals) or healthy corporate cash accruals / PAT demonstrating comfortable EMI coverage.

03

Bureau & Financial Standing

A bureau score of 750+ (CIBIL/CMR) with unblemished commercial debt servicing history, minimal unsecured exposure, and strong asset-to-liability ratios.

04

Vehicle Segment

Factory-new or authorized dealer-certified pre-owned luxury sedans, premium SUVs, sports coupes, and exotic imports from recognized automotive manufacturers.

Tailored Program Structuring: Lenders provide surrogate appraisal programs (e.g., Banking Turnover schemes, Liquid Investment surrogates, and High-Net-Worth fast tracks) to expedite high-ticket sanctions with minimal friction.
HIGH-TOUCH PROCESSING

Luxury Car Loan Documents Checklist

Documentation is tailored to individual or corporate entity profiles for streamlined and confidential underwriting.

A

Individual & Promoters KYC

Mandatory identification verified under RBI regulatory frameworks.

  • Valid PAN Card of applicant, co-applicant, or promoter.
  • Officially Valid Document (OVD): Passport, Driving License, or Voter ID.
  • Two recent passport-sized colour photographs.
  • Current proof of residence if differing from permanent identity records.
  • Signature verification proof from banker or valid passport.

Direct Relationship Managers coordinate doorstep document collection and digital KYC.

B

Financial Statements & Balance Sheets

Records establishing corporate profitability and personal cash flow.

  • Individuals/CXOs: Form 16, latest salary slips, and 2–3 years of filed ITRs.
  • Enterprises: 2 to 3 years of audited financials (P&L, Balance Sheet, Computation).
  • Latest 6 to 12 months' operative bank statements of primary personal and corporate accounts.
  • GST returns and business proof (COI, MOA/AOA, Partnership Deed, or Udyam).
  • Statement of existing loans and sanction letters to assess total group exposure.

Turnover and banking surrogates can be applied for qualifying high-turnover businesses.

C

Vehicle Pro Forma & Build Sheet

Specifications, bespoke options, and dealer quotation records.

  • Pro Forma Invoice / Quotation from an authorized luxury vehicle dealership.
  • Build sheet detailing optional packages, bespoke trims, and accessories.
  • Breakdown of ex-showroom price, Kerala Motor Vehicle road taxes, and insurance.
  • Booking receipt and token advance payment confirmation.
  • Extended warranty and OEM maintenance package invoices (if bundled).

Lenders offer up to 85%–95% on-road financing on select luxury brand partnerships.

D

Pre-Owned Luxury Vehicles (If Applicable)

Essential documentation for high-end pre-owned and exotic car purchases.

  • Original Registration Certificate (RC) verifying clear title and engine/chassis numbers.
  • Comprehensive vehicle service and maintenance history from the authorized OEM dealer.
  • Certified physical valuation report by the bank’s empaneled surveyor.
  • Active insurance policy and valid Pollution Under Control (PUC) certificate.
  • RTO transfer Forms 29, 30, and Form 34 hypothecation endorsement applications.

Vehicles must pass thorough encumbrance and chassis background checks via Parivahan Vahan.

Discretion & Confidentiality: Capital Solutions respects client privacy. Financial information is reviewed solely for lender qualification through secure banking channels. No banking passwords, credentials, or OTPs are ever requested.
CONCIERGE-LEVEL ROADMAP

How the Luxury Car Loan Process Works

A seamless, discreet financing pathway tailored to your demanding schedule.

Step 01 / Consult

Confidential Strategy

Connect with our private finance desk to discuss your chosen luxury vehicle, desired structure, and tax optimization goals.
Step 02 / Structure

Bespoke Structuring

Select an optimal structure—standard amortisation, balloon EMI, or corporate financing—matching your financial profile.

Step 03 / Sanction

KFS & Rate Acceptance

Review the formal sanction letter and standardized Key Facts Statement (KFS) detailing high-ticket APR, charges, and tenure terms.

Step 04 / Deliver

Disbursement & Handover

The lender issues the Delivery Order (DO) and disburses proceeds directly to the dealer, coordinating white-glove handover.

TRANSPARENT WEALTH BORROWING

Interest Rates, Structured Options & RBI Disclosures

Compare complete financing structures, effective APR, processing covenants, and regulatory frameworks before signing your premium credit facility.

₹

Interest Rates & Net APR

Premium car loan rates typically range from 8.25% to 11.50% p.a. depending on loan size, corporate standing, and vehicle segment. Review the comprehensive Annual Percentage Rate (APR) in your KFS, including all setup fees.

02

Processing & Capping

High-value loans often feature capped processing fees (e.g., flat charges rather than uncapped percentages) negotiated through private wealth channels. Applicable taxes and stamp duties apply as per Kerala statutes.

03

Structured Prepayments

Under RBI directives, floating-rate loans sanctioned to individual borrowers for non-business purposes cannot carry foreclosure or part-payment penalties. Fixed-rate or corporate commercial lines follow contractual terms.

Regulatory Directives & Borrower Rights

  • Standardised Key Facts Statement (KFS): All banks and NBFCs must deliver a comprehensive KFS prior to executing the loan agreement. The KFS outlines the sanctioned sum, tenure, exact amortization method, upfront charges, and all-inclusive APR.
  • Fair Practices on Penal Levies: In compliance with RBI regulations, charges for late payment or default must be levied solely as transparent, non-compounded "penal charges" and cannot be capitalized to charge additional compounding interest.
  • 30-Day Release of RTO Hypothecation (NOC): Upon full loan liquidation, lending institutions are mandated by RBI directions to issue the official No Objection Certificate (NOC) and Form 35 within 30 days to clear vehicle hypothecation from the Parivahan RTO registry.
  • Clear Corporate End-Use: Vehicle financing granted under corporate entities must adhere to authorized business resolutions and comply with statutory reporting regarding depreciation, balance sheet disclosures, and asset hypothecation filings (ROC Form CHG-1).
  • Ombudsman Mechanism: Borrowers retain the right to escalate unresolved grievances regarding processing commitments, sanction deviations, or bureau reporting delays directly to the RBI Integrated Ombudsman Scheme (cms.rbi.org.in).

Regulatory standards comply with current Reserve Bank of India retail and commercial banking directives. This summary provides educational guidance and is not a substitute for the official loan agreement.

CONDITIONS OF SANCTION

Luxury Vehicle Loan Terms & Conditions

Key contractual covenants governing high-ticket auto financing, security interest, and asset maintenance.

1. High-Ticket Sanctions & Margin

Loans exceeding ₹50 Lakhs are subject to tiered LTV benchmarks (typically 75% to 90% of on-road cost). The borrower contributes the designated equity margin directly to the dealership prior to disbursement.

2. Balloon & Structured Repayments

Where structured with balloon or residual payments (e.g., 20%–30% final installment), the borrower must liquidate the balloon amount, refinance under lender policy, or trade in the asset via dealer buy-back agreements.

3. Direct Dealer Disbursement

Loan proceeds are disbursed through secure institutional channels directly to the OEM dealership's verified account against a confirmed pro forma invoice and verified down-payment receipt.

4. Corporate Guarantees & Resolutions

For loans availed under private limited companies, LLPs, or corporate entities, appropriate Board Resolutions, ROC charge filings (Form CHG-1), and personal promoter guarantees may be required by the lending institution.

5. Comprehensive Insurance & Zero Dep

The luxury vehicle must be covered by comprehensive motor insurance throughout the loan tenure, with the financier endorsed as sole hypothecated lienholder. Zero-depreciation, engine protector, and Return-to-Invoice (RTI) covers are mandatory.

6. RTO Hypothecation Endorsement

The borrower must ensure that the vehicle’s Smart Card Registration Certificate (RC) reflects the lending bank’s hypothecation endorsement via Form 34 filed with the Kerala Motor Vehicles Department within statutory timelines.

7. Asset Inspection & Maintenance

The borrower agrees to maintain the luxury vehicle in roadworthy condition and adhere to authorized OEM service schedules to protect the asset's residual collateral value.

8. Credit Bureau Information

Performance on the loan account is reported monthly to CIBIL, Experian, Equifax, and CRIF High Mark in compliance with the Credit Information Companies (Regulation) Act.

Capital Solutions service disclaimer
Capital Solutions operates as an independent financial consultancy and loan facilitation desk in Kerala. Capital Solutions is not a bank, non-banking financial company (NBFC), or credit decision-maker under RBI regulations. Final credit sanction, interest margins, balloon structures, and disbursements are executed solely at the discretion of partner lending institutions.
PREMIUM VEHICLE FINANCE IN KERALA

Strategic Financial Architecture for Luxury Car Purchases

Kerala boasts one of the most discerning automotive markets in India, with high demand for premium sedans, performance SUVs, and bespoke exotics. Navigating luxury auto finance requires more than checking monthly EMIs. It involves optimizing balance sheet leverage, comparing floating versus fixed structures, securing competitive interest rate caps, and coordinating swift delivery orders with brand dealerships across Kochi, Kozhikode, and Thiruvananthapuram.

Loans for luxury and exotic vehicles range from ₹30 Lakhs to ₹5 Crores or more, covering 80% to 95% of the on-road price. For ultra-high-net-worth clients and top corporate entities with established banking relationships, select institutions can approve up to 100% ex-showroom financing.
In addition to standard EMIs, luxury finance offers Step-Up repayment (lower EMIs in initial years that increase annually) and Balloon repayment structures (lower monthly EMIs with a predetermined lump sum at tenure completion), allowing borrowers to manage cash flows efficiently.
Purchasing through a company or LLP allows the business to claim allowable vehicle depreciation and deduct interest payments as business expenditures, optimizing corporate tax liabilities. Consult your chartered accountant to determine the optimal structure for your balance sheet.
ACQUISITION CHECKLIST

Before Finalizing Your Marque

  • Decide between Individual, Corporate, or LLP borrower profile.
  • Obtain official dealer pro forma invoice with options build sheet.
  • Evaluate balloon versus traditional amortisation schedules.
  • Ensure comprehensive insurance includes Zero-Dep & Engine Protector.
  • Verify that processing fees are capped rather than open-ended.
  • Review the standardized KFS for net APR and all covenants.
  • Check delivery schedule commitments with the OEM dealership.
  • Confirm hypothecation documentation terms with private desk.
Connect with Private Desk →

Final sanctions, interest rates, balloon structures, and loan covenants are decided exclusively by partner banks and NBFCs.

YOUR QUESTIONS ANSWERED

Luxury Car Loan FAQs

Clear answers regarding premium car finance, corporate borrowings, balloon payments, and regulatory guidelines.

01 What documents are needed for a luxury car loan?
Borrowers provide KYC documentation, 2 to 3 years of audited financials or Form 16/ITRs, 6 to 12 months of primary bank statements, business registration details (for corporate borrowers), and an official pro forma invoice from an authorized luxury dealership.
02 How do interest rates for luxury cars compare to normal car loans?
Because luxury car buyers typically present strong credit ratings and established financial profiles, premier private banks offer competitive interest rates (typically 8.25% to 10.50% p.a.), often comparable to or lower than standard retail rates.
03 Can I finance a pre-owned luxury or exotic vehicle?
Yes, banks and specialized NBFCs finance certified pre-owned luxury cars. The car must undergo an inspection and valuation by the lender’s authorized surveyor, and vehicle age plus loan tenure should typically not exceed 8 to 10 years at maturity.
04 What is a Key Facts Statement (KFS) in high-ticket car loans?
A KFS is an RBI-mandated document that details the total sanctioned credit, interest rate, upfront processing fees, all-inclusive Annual Percentage Rate (APR), and recovery amortisation schedule before loan execution.
05 What is the maximum repayment tenure for a luxury vehicle?
Tenures for brand-new luxury cars range from 1 to 7 years (up to 84 months). For pre-owned luxury cars, the maximum tenure is usually capped at 3 to 5 years depending on vehicle age.
06 Can NRI business owners avail luxury car financing in Kerala?
Yes. NRIs can finance luxury vehicles in Kerala by providing overseas employment/business documents, NRE/NRO bank account statements, and including a resident Indian co-applicant or guarantor.
07 Can insurance and extended warranty packages be funded?
Yes. Lenders frequently bundle comprehensive motor insurance, multi-year zero-depreciation coverage, extended OEM warranties, and service maintenance packages directly into the overall loan sanction.
08 Are there foreclosure charges on luxury vehicle loans?
Under RBI directives, regulated lenders cannot levy foreclosure or prepayment penalties on floating-rate term loans granted to individual borrowers for non-business purposes. Fixed-rate or corporate commercial facilities follow contractual terms.
09 Does Capital Solutions approve luxury car loans directly?
No. Capital Solutions operates as an independent financial consultancy and application advisory desk. Sanctioning, interest rate determination, and fund disbursement are handled exclusively by RBI-regulated banks and NBFCs.
10 How is hypothecation handled for premium vehicle purchases?
The dealer executes RTO Form 34 with the Motor Vehicles Department during registration, ensuring that the lending bank’s lien is endorsed on the smart card RC and Parivahan Vahan portal records.
11 Which lenders offer dedicated luxury car financing desks?
Private sector institutions including HDFC Bank, ICICI Bank, Axis Bank, Kotak Mahindra Bank, BMW Financial Services, and Mercedes-Benz Financial Services maintain specialized wealth desks for luxury and exotic cars.
12 How fast can a high-ticket luxury car loan be sanctioned?
For qualified applicants with clean credit records and complete financial statements, private wealth desks often issue sanctions within 48 to 72 hours, facilitating prompt Delivery Order issuance.