CAPITAL SOLUTIONS · VEHICLE FINANCE

Your Dream Car.
Your Smarter Drive.

Looking for a new car loan or used car loan in Kerala? Capital Solutions helps you explore vehicle financing options, understand documentation requirements and prepare your application for consideration by eligible lenders.

✓ Application guidance ✓ Clear documentation ✓ Lender-specific terms
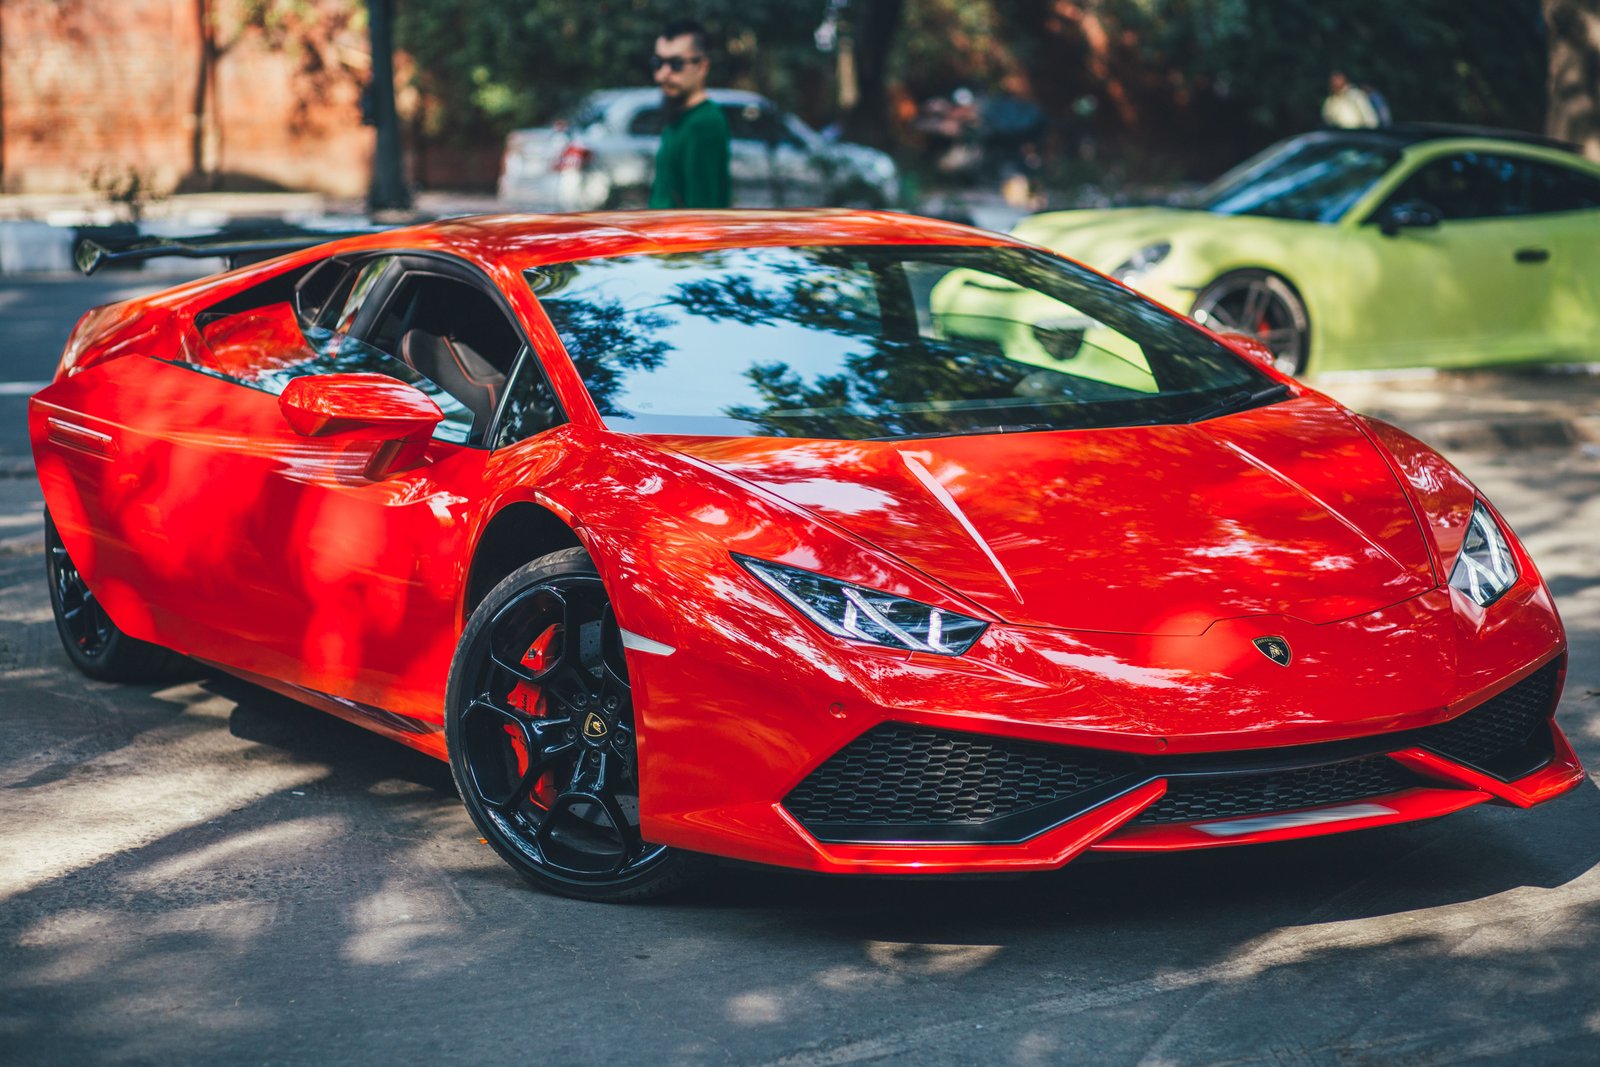
Car loan and vehicle financing assistance by Capital Solutions in Kerala
01. New Car
Financing options for a new vehicle purchase.
02. Used Car
Explore eligible pre-owned vehicle finance.
03. Luxury Car
Ask about financing for premium vehicles.
04. Car Refinance
Check options against an eligible existing vehicle.
KNOW BEFORE YOU APPLY

Car Loan Eligibility Criteria

Eligibility differs between banks and NBFCs. Lenders assess your financial profile, the proposed vehicle and your ability to repay the loan before making a lending decision.

Discuss Your Eligibility →
01

Age & Residency

Applicant age, residency status and maximum age at loan maturity must meet the chosen lender's criteria.

02

Income & Employment

Salary, business income, employment stability, existing obligations and repayment capacity may be assessed.

03

Credit History

Credit bureau information and repayment history can influence approval, loan amount and pricing.

04

Vehicle Assessment

The car's value, age, condition, registration and eligibility under the lender's policy are relevant.

Important: There is no single age limit, minimum salary or credit score applicable to every car loan. Confirm the latest criteria directly with the proposed lender.
PREPARE YOUR APPLICATION

Car Loan Documents Required

Use this general checklist to prepare for a car loan application. The final document list depends on the lender, applicant profile, vehicle type and applicable KYC requirements.

A

Identity & Address Proof

Documents used to establish identity and complete KYC.

  • PAN card, where required by the lender and applicable law.
  • Valid identity and address documents accepted by the lender.
  • Aadhaar or another permitted KYC method, where applicable.
  • Recent photograph, if requested.
  • Additional address proof if the current address differs.

The lender determines which documents are accepted and whether additional verification is needed.

B

Salaried Applicant Documents

Evidence of employment, income and repayment capacity.

  • Completed loan application form.
  • Recent salary slips, as requested.
  • Bank statements showing salary credits.
  • Form 16 or income-tax returns, where required.
  • Employment details or additional income proof, if requested.

Some lenders may request different statement periods or waive certain documents for eligible existing customers.

C

Self-Employed & Business Applicants

Evidence of business activity and financial performance.

  • Personal and business bank statements, as applicable.
  • Income-tax returns for the requested assessment years.
  • Profit and loss statements and balance sheets, where required.
  • Business registration or proof of business activity, if applicable.
  • GST returns or other supporting financial records, if requested.

The lender may request audited statements or additional records depending on the business structure and loan profile.

D

Vehicle & Purchase Documents

Documents needed to assess the proposed car and transaction.

  • Dealer quotation, pro forma invoice or sale agreement.
  • Vehicle model, price and variant details.
  • Registration Certificate (RC) for an eligible used vehicle.
  • Seller and ownership documents for a pre-owned vehicle.
  • Insurance, valuation, transfer or hypothecation documents, as applicable.

The lender may require further vehicle inspection, valuation, registration or disbursement documentation.

Document safety: Submit sensitive documents only through verified lender channels or authorised processes. Do not share OTPs, PINs, passwords or banking credentials with anyone claiming to arrange a loan.
A CLEARER APPLICATION JOURNEY

How the Car Loan Process Works

Understand the typical stages involved, from your initial enquiry through lender assessment and vehicle delivery.

Step 01 / Enquire

Share Your Requirements

Tell us whether you need new or used car finance, the approximate vehicle price and your preferred budget.
Step 02 / Prepare

Review Your Documents

Prepare KYC, income and vehicle documents relevant to your circumstances and the lender's checklist.

Step 03 / Assess

Lender Verification

The lender reviews eligibility, credit information, vehicle details, repayment capacity and supporting documents.

Step 04 / Decision

Review the Offer

If approved, review the sanction terms, Key Facts Statement, total charges and repayment schedule before accepting.

TRANSPARENT BORROWING

Interest Rates, Fees & RBI Disclosures

A car loan should be assessed by its overall cost, not only by its advertised interest rate. Review the written offer and all applicable charges before making a decision.

₹

Interest Rate & APR

Compare the offered interest rate and the Annual Percentage Rate (APR), where applicable. The rate may depend on the lender's pricing policy, credit profile, vehicle and tenure.

02

Processing & Other Fees

Check processing, documentation, valuation, statutory, registration-related and other applicable charges. Applicable taxes should also be accounted for.

03

Late Payment & Closure

Check the consequences of missed EMIs, applicable penal charges, bounce charges, foreclosure terms and part-payment conditions in the relevant agreement.

Important regulatory and borrower protections

  • Key Facts Statement (KFS): For covered retail and MSME term loans from regulated entities, RBI's KFS framework requires key loan information, including applicable APR and charges, to be disclosed in a standardised format before the borrower enters the contract.
  • Clear loan terms: Review the sanctioned amount, tenure, EMI, interest type, applicable charges, security requirements and repayment terms in the lender's offer and loan agreement.
  • Penal charges: Applicable penal charges and the circumstances in which they are imposed should be disclosed under the lender's applicable regulatory requirements and contractual terms.
  • Digital lending: If a transaction is covered by RBI's digital lending rules, applicable disclosures, consent requirements and regulated lender responsibilities must be followed.
  • Grievances: Raise service complaints with the relevant lender first. If the issue falls within the RBI Integrated Ombudsman Scheme and remains unresolved under its eligibility conditions, the RBI complaint mechanism may be available.

Regulatory applicability depends on the product, lender category and current RBI directions. This summary is educational and is not a substitute for the applicable law, lender policy or loan agreement.

READ BEFORE PROCEEDING

Car Loan Terms & Conditions

The following general information helps applicants understand common loan conditions. The final terms are those set out by the actual lending institution in its current written offer.

1. Application & Verification

Applicants must provide complete and accurate information and the requested supporting documents. The lender may conduct KYC, income, employment, credit and vehicle checks.

2. Credit Approval

Submission of an application does not guarantee approval, a particular loan amount, a particular interest rate or disbursement. The lender makes the final credit decision.

3. Down Payment & Margin

The borrower may need to contribute a down payment or margin. The required amount depends on the vehicle price, valuation, lender policy and approved loan amount.

4. Interest & Repayment

The applicable rate, EMI, tenure, interest calculation method and repayment dates are governed by the sanction terms and executed agreement.

5. Security & Hypothecation

Vehicle loans commonly involve a security interest in the financed vehicle and applicable hypothecation formalities. Follow the lender's instructions for registration and closure.

6. Insurance & Vehicle Documents

Maintain legally required vehicle insurance and comply with applicable registration and other legal requirements. Any lender-specific insurance conditions should be verified before accepting the offer.

7. Default & Prepayment

Missed repayments may result in applicable charges and contractual enforcement measures. Part-payment and foreclosure rights or charges depend on the agreement and applicable law.

8. Privacy & Consent

Applicant information should be collected and shared only through appropriate, disclosed and authorised processes. Review the lender's privacy notice and consent terms.

Capital Solutions service disclaimer
This website provides general information and enquiry assistance. Unless expressly authorised and disclosed in a separate agreement, Capital Solutions should not be represented as the lender, the credit decision-maker or an RBI-regulated bank or NBFC. The applicable lender agreement governs the loan. Any service fees, if applicable, must be separately disclosed and agreed before a service is provided.
CAR LOAN ASSISTANCE IN KERALA

Find the Right Car Financing Option for Your Needs

Choosing a car loan involves more than finding a vehicle and selecting an EMI. Applicants should compare the total borrowing cost, required down payment, repayment period, documentation, vehicle eligibility and conditions that apply throughout the loan.

A new car finance application may require identity and address proof, income records, bank statements and a dealer quotation. Additional documents may be requested depending on the lender, your employment or business profile and the vehicle being purchased.
Pre-owned car financing can involve checks relating to vehicle age, condition, valuation, ownership, registration and remaining useful life. Your income, credit profile and repayment capacity may also be considered. The eligible loan amount and tenure depend on the individual lender's policies.
A lower advertised interest rate does not necessarily mean a lower total borrowing cost. Compare the written interest rate, applicable APR where provided, processing fees, statutory charges, insurance costs where relevant, late-payment charges and prepayment conditions. Review the lender's written offer before accepting the loan.
QUICK CHECKLIST

Before You Apply

  • Estimate your comfortable monthly repayment.
  • Check your current credit report for errors.
  • Prepare accepted identity and address documents.
  • Collect the income documents requested by the lender.
  • Confirm the vehicle price and required down payment.
  • Compare written offers and total applicable costs.
  • Read the KFS, sanction letter and loan agreement.
Request Document Guidance →

Final eligibility, interest rates, loan amounts and documentation requirements are determined by the relevant lender.

YOUR QUESTIONS ANSWERED

Car Loan FAQs

Answers to common questions about eligibility, documentation, interest rates and car loan repayment.

01 What documents are required for a car loan?
Common requirements include a completed application, accepted identity and address proof, PAN where required, income documents, bank statements and vehicle purchase documents. Salaried and self-employed applicants may have different income documentation requirements.
02 Can I apply for a car loan if I am self-employed?
Yes, eligible self-employed applicants may apply. The lender can assess business stability, income, tax returns, bank statements and other financial documents under its current eligibility criteria.
03 Is a high credit score necessary for a car loan?
A strong credit history may improve your chances of obtaining favourable terms, but each lender sets its own credit assessment criteria. Approval is not determined by a single score alone in every case.
04 Can I get a loan for a used or second-hand car?
Eligible used vehicles may be financed by banks and NBFCs. The vehicle's age, condition, value, ownership documents and the applicant's financial profile can affect the offer.
05 What determines my car loan interest rate?
Pricing may depend on the lender, credit profile, income, loan amount, vehicle type, repayment tenure and applicable pricing policy. Obtain a current written offer before comparing lenders.
06 What is a Key Facts Statement (KFS)?
A KFS is a standardised disclosure containing key loan information, including applicable APR and charges. RBI's KFS framework applies to covered retail and MSME term loans provided by regulated entities. Review the KFS supplied for your particular loan before entering into the contract.
07 Are processing fees and other charges applicable?
They may be. The lender may charge applicable processing, documentation, valuation, statutory or other disclosed fees. Check the current schedule of charges and your individual offer for exact amounts.
08 Can I repay my car loan early?
Early repayment or part-payment depends on the loan product, contract and applicable law. Ask the lender for its current foreclosure or part-payment terms and any applicable charges.
09 Does Capital Solutions guarantee loan approval?
No. An enquiry or assistance with an application does not guarantee approval, a particular interest rate or a specific loan amount. The lender makes the final decision after assessing the application and supporting documents.
10 How can I enquire about a car loan with Capital Solutions?
Contact Capital Solutions through the WhatsApp enquiry link on this page. Share your general requirements to begin an enquiry. Do not send OTPs, passwords or sensitive banking credentials through chat.
11 Are the terms the same at SBI, HDFC Bank and Shriram Finance?
No. Eligibility, interest rates, loan tenure, documentation, charges and vehicle conditions can differ by provider and product. Check the current official terms of the lender you intend to approach.
12 How long does a car loan application take?
Processing time varies depending on the lender, the completeness of documents, verification requirements and the complexity of the application. A specific timeline cannot be guaranteed.